A scholarship offer is exciting, but the amount on the letter is only one part of the decision. The funding gap is the cost you still need to cover after confirmed awards are applied. Calculating it before you accept a place helps you test whether your plan is workable across the whole programme, including expenses due before the first scholarship payment.
Use one period and one currency
Choose an academic year or term as your unit. Gather the institution’s published tuition and required fees for your programme and fee status, then its estimated living costs. Add expenses that the standard estimate may leave out: travel, visa or residence charges, deposits, books, equipment and health cover. Convert figures to one currency for planning, record the exchange rate and date, and allow a buffer for changes. Do not mix a one-year stipend with the total cost of a two-year course.
EducationUSA’s financial planning guidance includes tuition, fees and living expenses in the overall budget and cautions that many awards only partially cover costs. The same logic applies outside the United States, though each destination’s fee and immigration rules differ.
The calculation
Funding gap = total eligible study and living costs − confirmed usable funding. Break the calculation into tuition, living and one-time costs. “Usable” means an award that you have actually been granted, applies to your chosen programme and period, and can pay the expense in question. A tuition-only award cannot be counted again against rent. A possible assistantship or competitive scholarship is not confirmed funding.
Make a table with columns for item, amount, source, award coverage, due date and remaining balance. Write “not specified” when the award terms are silent. This is more useful than treating an unknown as zero.
A worked example
Imagine one academic year with tuition and mandatory fees of 18,000, living costs of 11,000 and one-time arrival costs of 2,000. The total is 31,000. A confirmed scholarship pays 18,000 directly toward tuition and 6,000 as a living allowance. The remaining gap is 7,000: 5,000 in living costs plus 2,000 in arrival costs. These numbers are illustrative arithmetic, not an estimate for a real institution or country.
Now examine cash flow. If the 6,000 allowance arrives after enrolment, you may still need money upfront for a housing deposit and travel. “Affordable over the year” does not necessarily mean “payable when due.” Ask the university when funds are released and whether a deposit or fee is required before the first instalment.
Calculate every year of the course
Repeat the table for each year. Check whether tuition rises, the stipend changes, summer costs are covered and the scholarship renews automatically or conditionally. If the award lasts one year of a longer programme, do not carry it forward without written confirmation. If a placement, research trip or delayed completion changes costs, model that separately.
Where the award has a grade or enrolment requirement, record the condition beside the funding amount. If a second scholarship could reduce the first, do not simply add both headline figures. Ask how the university coordinates awards. Our practical Australia student budget shows the kind of destination-specific expense research to combine with an award calculation; use current institutional prices for your own programme.
Do not count uncertain income as guaranteed
Part-time work, family help, loans and exchange-rate gains may form part of a plan, but label them separately by certainty and timing. Work eligibility varies by visa and location, jobs are not guaranteed, and some scholarships restrict employment. A lender’s advertised product is not an approved loan. Identify what you can demonstrate as available funds if the institution or immigration authority requires evidence.
Compare two offers using the same worksheet
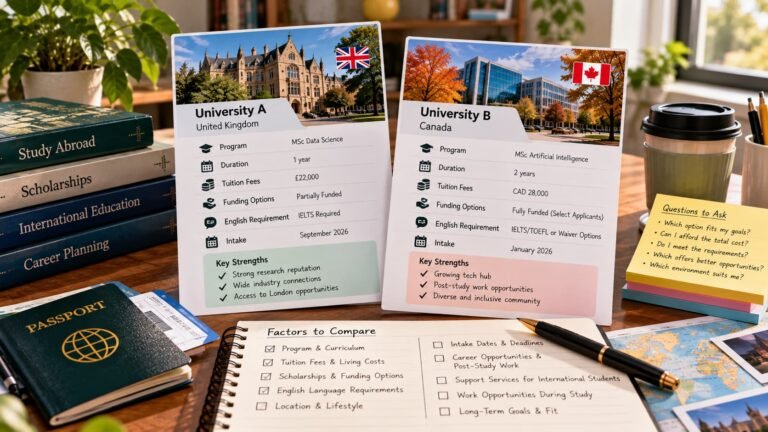
Suppose one university offers full tuition at a higher-cost location and another offers a smaller tuition discount where housing is less expensive. Run the calculation for both with each institution’s own published figures. Keep programme length, currency and payment timing visible. A lower annual gap is only meaningful if the academic fit and total duration also work for you.
Stress-test the result: what if housing costs rise, the stipend is paid late or the award is not renewed? You do not need to predict the future precisely, but you do need to know which assumptions could make the plan fail. Record a cautious estimate alongside a best-case one, and distinguish written guarantees from hopes. If the institution publishes several housing price bands, use one that reflects accommodation you can actually access rather than the cheapest theoretical option.
If you are comparing different countries, check how each destination asks international students to demonstrate funds for immigration purposes. A personal budget and an official proof-of-funds requirement answer different questions; verify the current rule with the relevant government authority instead of treating the scholarship letter as automatically sufficient.
Questions for the scholarship office
- Which tuition and compulsory fees does this award pay?
- Is the living allowance paid monthly, by term or after enrolment?
- Are insurance, travel, visa costs or housing deposits included?
- How many years are funded, and what must I do to renew?
- Can I combine this award with another grant or assistantship?
Keep the answer in writing. If the gap is still beyond your means, compare institutions and alternative awards before making a non-refundable commitment. Browse Seglas scholarships for options, then return to each provider’s current offer and your own budget for the final decision.